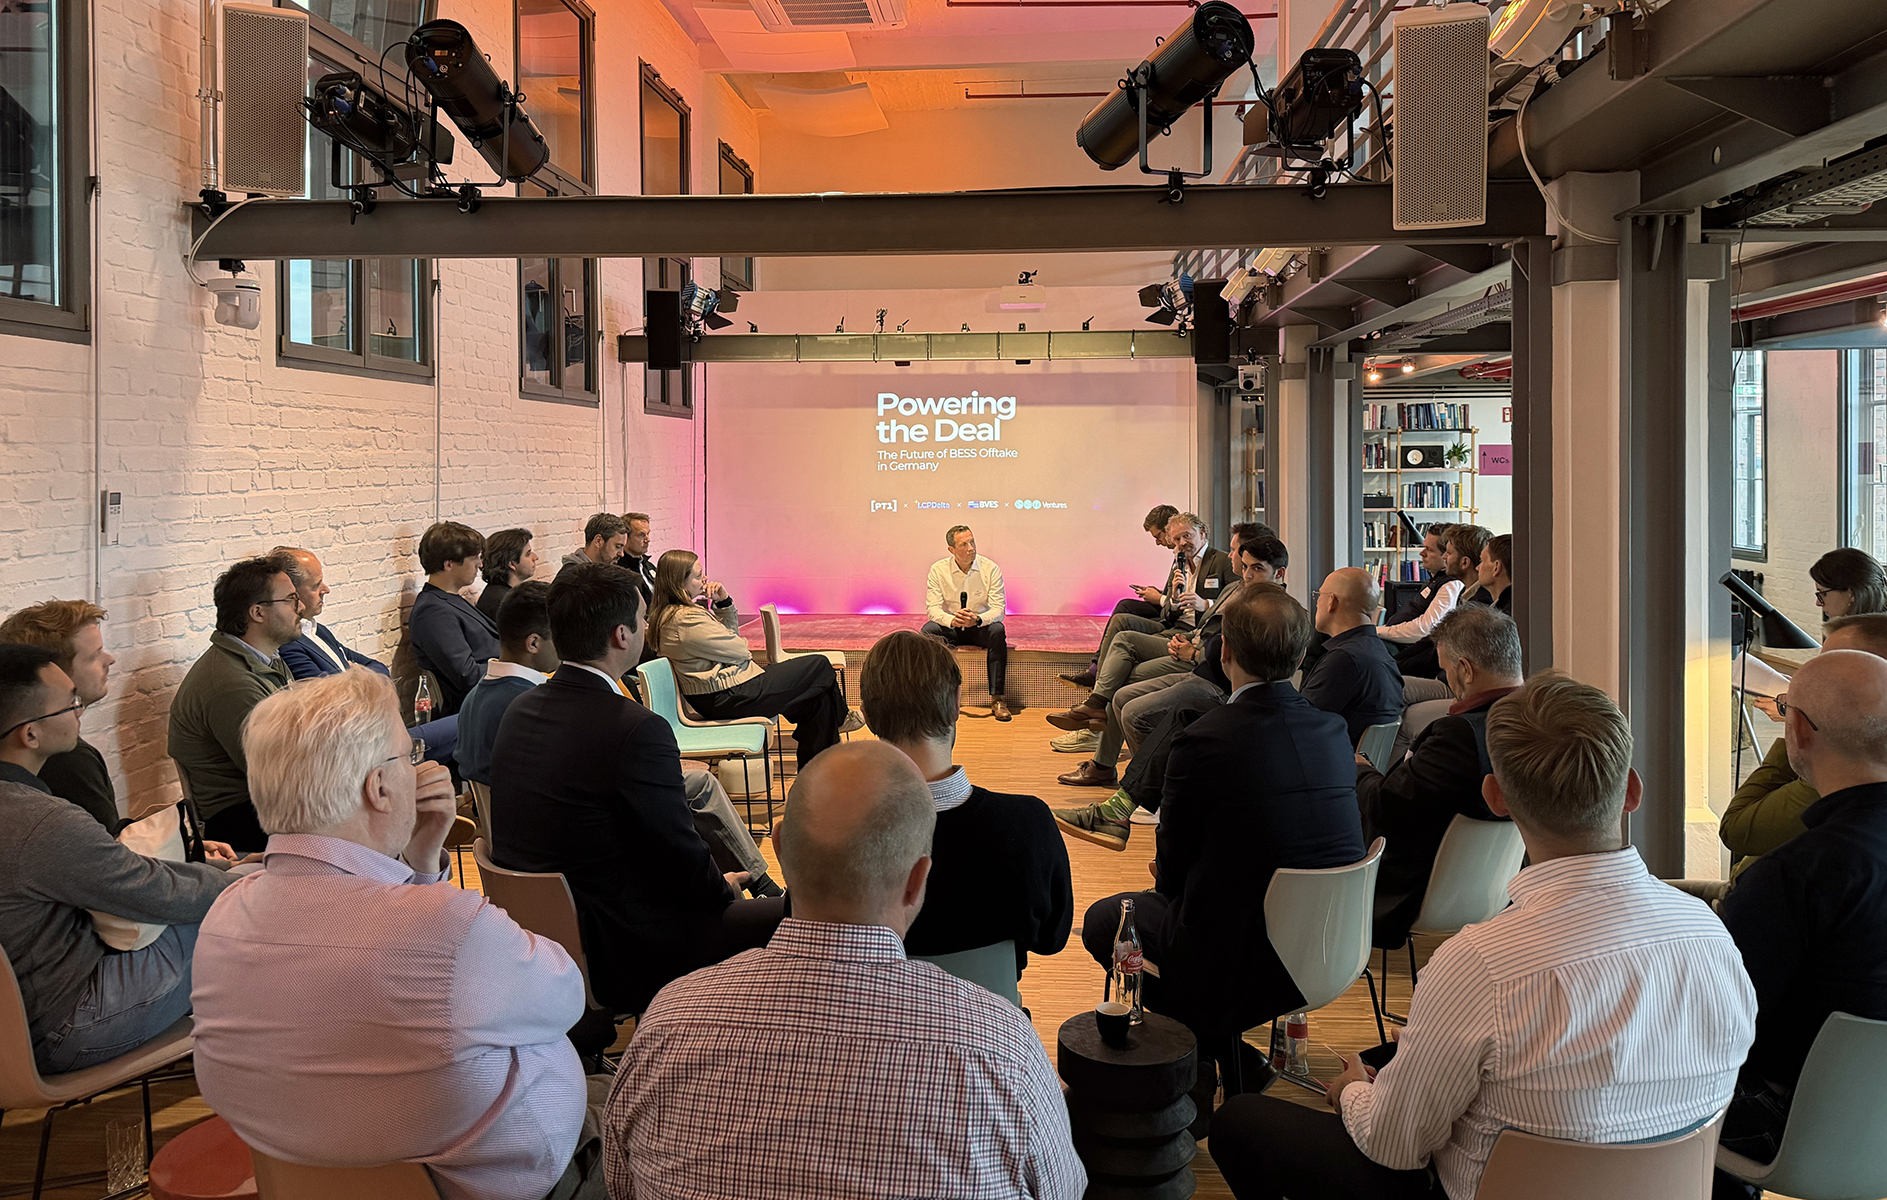
On 13 October, the evening before the 4th BVES Investor Summit Europe opened in Berlin, we hosted the Summit's official pre-event at the PT1 Clubroom. Together with BVES, LCP Delta and SET Ventures, we brought banks, optimizers, IPPs, EPCs, utilities and investors around one table. The question we put to them sounds technical, but it decides whether a lot of battery projects in Germany get built at all.
Some context first. BESS stands for battery energy storage systems, large batteries connected to the grid that charge when power is cheap and plentiful and discharge when it is scarce. Germany's pipeline of these projects is growing fast. Whether they get financed increasingly comes down to a part of the deal that rarely makes headlines: the offtake, meaning the contract that fixes who uses the battery's capacity or output, and on what terms.
Why offtake decides bankability
A battery that earns its money purely on the open market, what the industry calls merchant, lives with every swing in prices. For a while that worked well, because balancing markets (where grid operators pay for short-term flexibility to keep frequency stable) paid generously. Those revenues are now compressing. At the same time, negative-price hours are piling up: hours with so much solar and wind on the grid that producers pay to get rid of their power.
Lenders react the way lenders do. They want to see predictable cash flows before they put debt into a project. So financing is shifting away from equity that bets on the market toward structured debt, backed by offtake and tolling contracts. In a tolling agreement, a third party such as a trader or utility pays the owner a fee to use the battery and takes over the trading risk. For a developer, the offtake has become the thing that makes a project bankable, meaning a bank is willing to finance it.
A growing menu of structures
The market has responded with a new generation of contracts. Fixed-floor tolling guarantees the owner a minimum income. Price swaps exchange a variable market price for a fixed one. Collars set both a floor and a cap, so the owner gives up part of the upside in return for protection on the downside. Hybrid PPAs (power purchase agreements) bundle renewable generation and storage into one supply contract, and revenue-share models split whatever the battery earns between owner and optimizer. Each of these draws the line between developer, lender, optimizer and trader in a different place.
Which structure fits depends heavily on the project. A battery co-located with a solar park that charges exclusively from green power keeps its EEG privileges, which changes its economics considerably. Tri-location projects go a step further and combine PV, wind and storage behind a single grid connection. Co-location in general means the battery's revenues are tied to the generation next to it. A contract that works for a standalone battery can be a poor fit for any of these.
The evening
Four short expert talks opened the evening. Gerrit Lühring (BVES), Sebastian Sunderbringk (Alpiq), Thomas Antonoli (Terra One) and Kristofer Fröjd (Decade Energy) each looked at the question from their own side of the market. Then the room took over. The roundtable worked through what is actually bankable today, where lenders draw their lines and how the market is likely to move. One question kept coming back: is Germany heading toward standardized BESS offtake structures? Standard contracts would make deals faster and cheaper to close. They would also flatten differences between projects that, as the business cases above show, can be quite large.